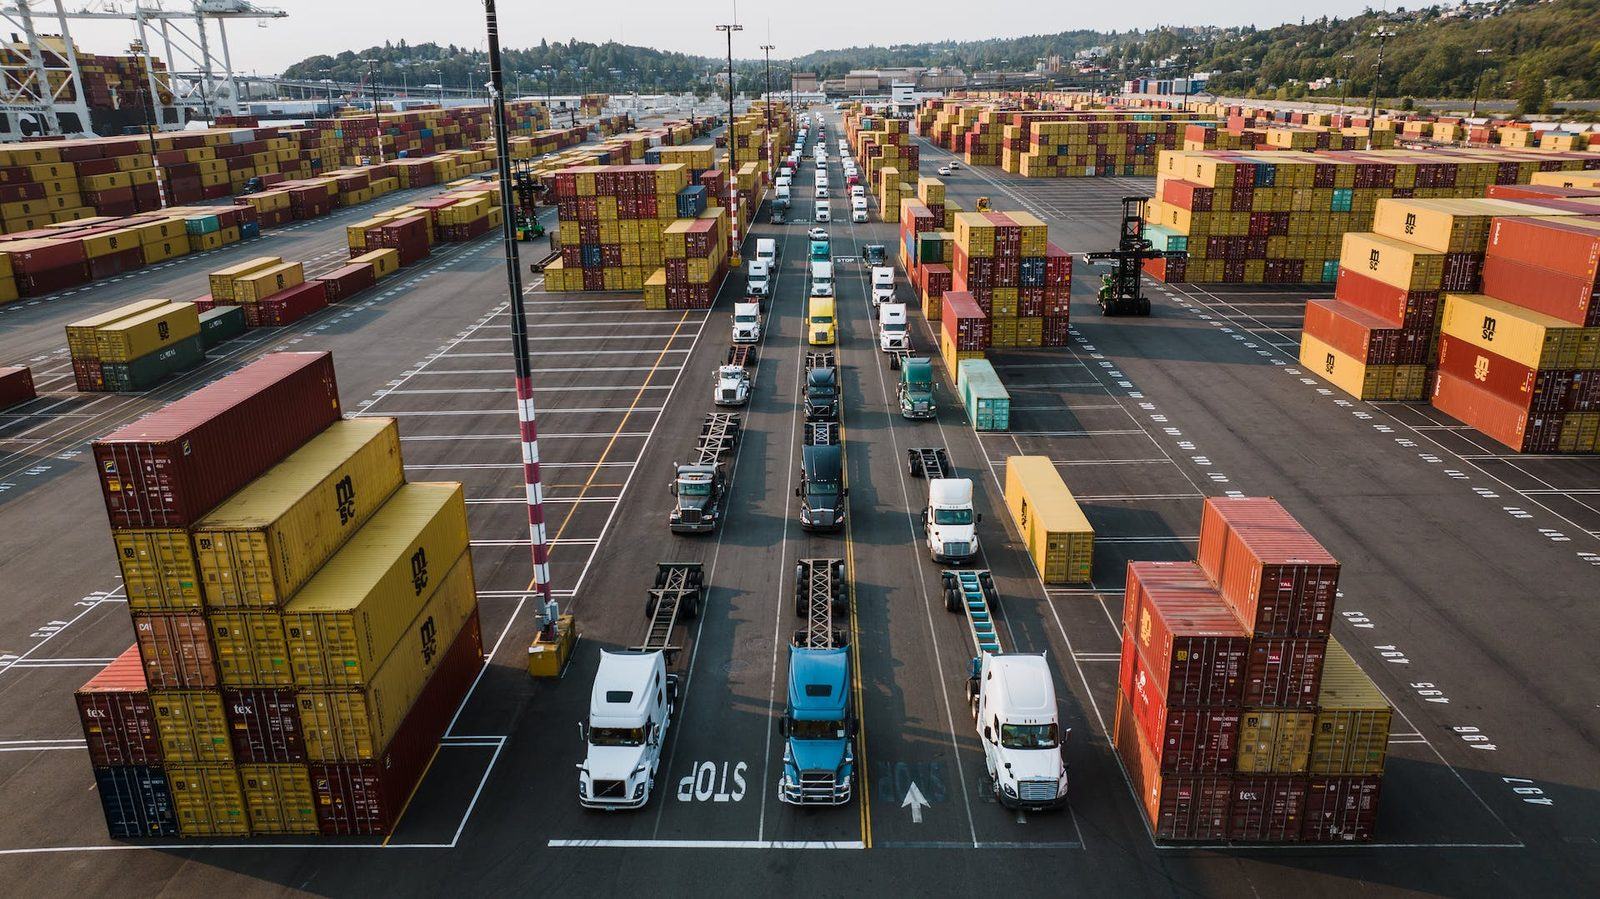
Ghanaian import duty is charged on the CIF value: the cost of the goods, the insurance and the freight, converted to cedis at the prevailing rate. Everything else is calculated on top of that base, which is why the freight rate matters more than it looks.
The order of calculation
- CIF value: goods + insurance + freight, in cedis.
- Import duty: the HS-code rate applied to the CIF value (commonly 5%, 10% or 20%).
- NHIL and GETFund: percentages applied to the CIF value, not to the duty.
- VAT: applied to CIF + duty + NHIL + GETFund, which is why it is larger than the nominal rate suggests.
- Other levies: ECOWAS levy, examination and processing fees, and any regulatory charge specific to the goods.
A worked example
Take a consignment with a CIF value of GHS 100,000 and a duty rate of 20%. Duty is GHS 20,000. NHIL at 2.5% and GETFund at 2.5% add GHS 5,000. VAT at 15% is then charged on GHS 125,000, giving GHS 18,750. Before any handling charge, the assessment is already GHS 43,750, or 43.75% of the CIF value.
The number importers forget is not the duty rate. It is that VAT is charged on the duty.
Do this before you commit
Ask for the classification and a duty computation in writing against your actual invoice, not a rule of thumb. Then check whether the goods attract a concession, an exemption or a reduced rate under an applicable regime. Getting this wrong in either direction is expensive: one costs you margin, the other costs you a query at the counter.